Payments processing major Adyen has published a Q3 2026 earnings update that sees the company prioritise investment over near and medium-term profit margins as it looks to capitalise on key recent acquisitions.
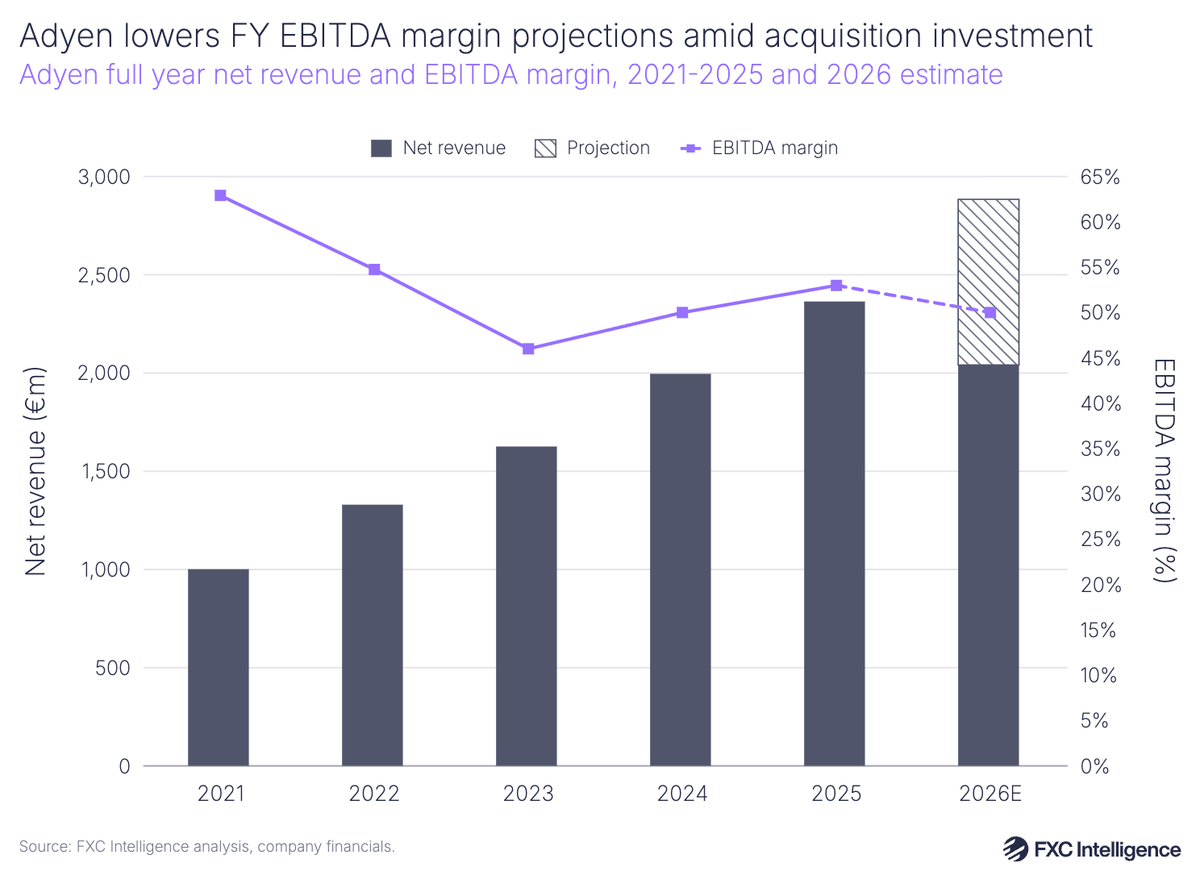
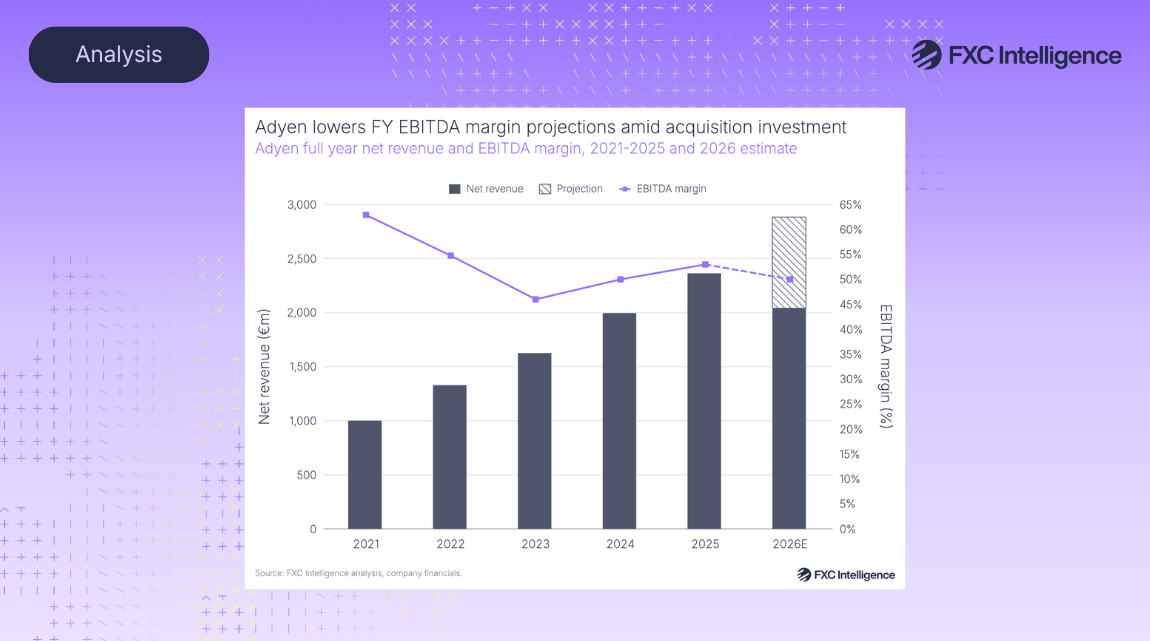
The company reported a 23% YoY increase in net revenue in Q3 2026 to €738.1m (c. $821m) and is on track to realise its FY 2026 guidance of 21-23% net revenue growth, which would see it achieve full-year net revenue of around $2.9bn (c. $3.2bn). It has also reported a 30% YoY increase in processed volume as it grows ahead of the wider market, including adding a “healthy cohort” of new enterprise customers.
However, the company has reduced its FY 2026 EBITDA margin projections to 50%, down from its H1 2026 projection of 52%, and has opted to discontinue its medium-term EBITDA objective. This is the result of the company conducting an accelerated investment initiative as a result of “strong merchant interest” off the back of its enhanced platform, aided by its recent acquisitions of loyalty and promotions platform Talon.One and usage-based billing platform Orb.
Talon.One is enabling the company to enhance the in-store loyalty aspect of its Unified Commerce solution, while Orb enables Adyen to better serve companies that charge by usage, such as AI companies that charge by tokens, compute or API calls.
To support its investment, Adyen has also doubled down on hiring at a time when competitors such as PayPal are making layoffs. The company reports adding 177 net-new team members in Q3 2026, in addition to the 399 added via the acquisition of Talon.One and Orb, and is now targeting 1,000-1,100 net new full-time equivalents in 2026, or 550-650 excluding its acquisitions.
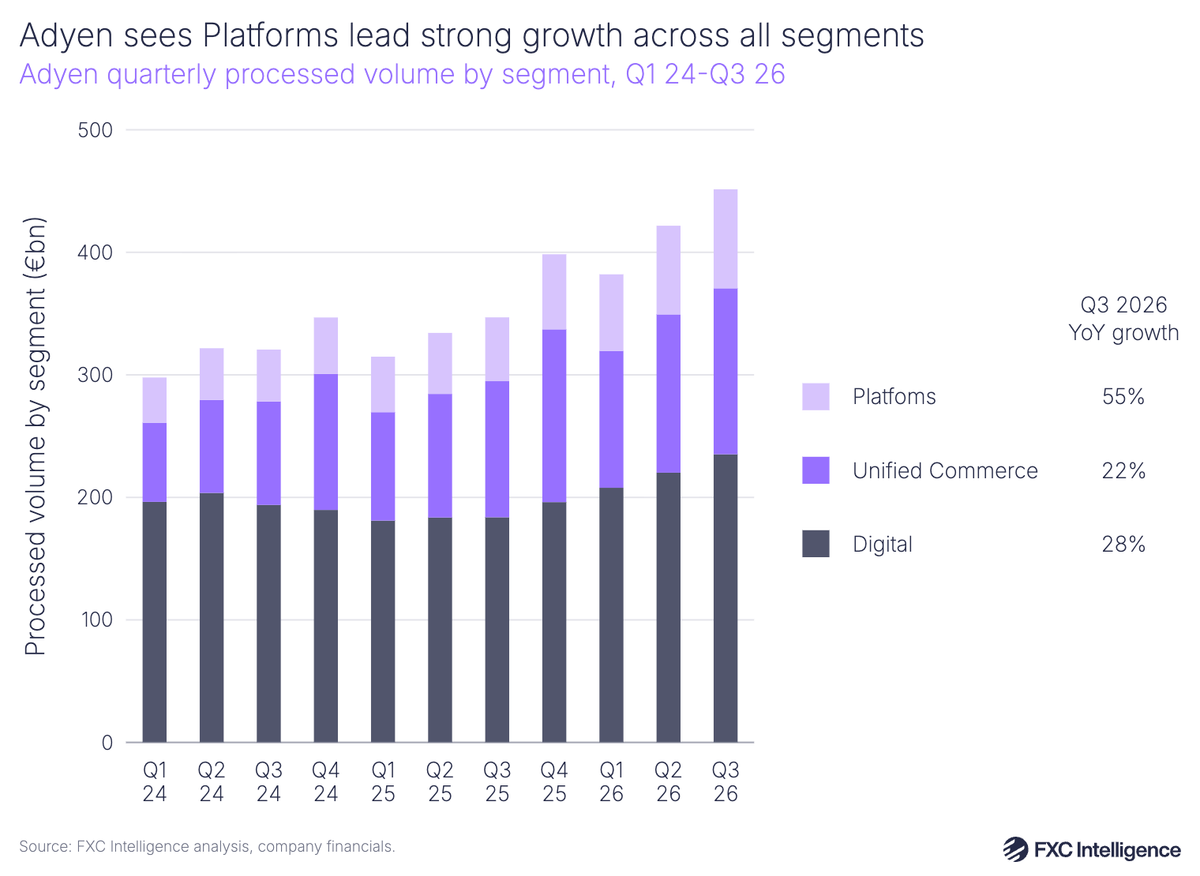
These investments are translating into gains across all three of its segments. Unified Commerce saw Talon.One help drive a 29% YoY gain in net revenue to €250.5m (c. $279m), while its processed volume increased by 22% YoY. Meanwhile, its Digital solution saw a 16% YoY increase in net revenue and a 28% YoY increase in processed volume as the company’s tiered pricing structure helped grow business with its existing large enterprise customers, particularly those in travel and content-related industries.
However, its Platform business saw the biggest gains, with a 46% YoY increase in net revenue to €100.2m (c. $112m) and a 55% increase in processed volume. The company in particular highlighted key growth among SaaS providers, financial services and insurance, and now has 46 Platform customers processing more than €1bn annually, up from 37 in Q2 2026. However, it sees its longer term opportunities for Platform growth in smaller merchants.