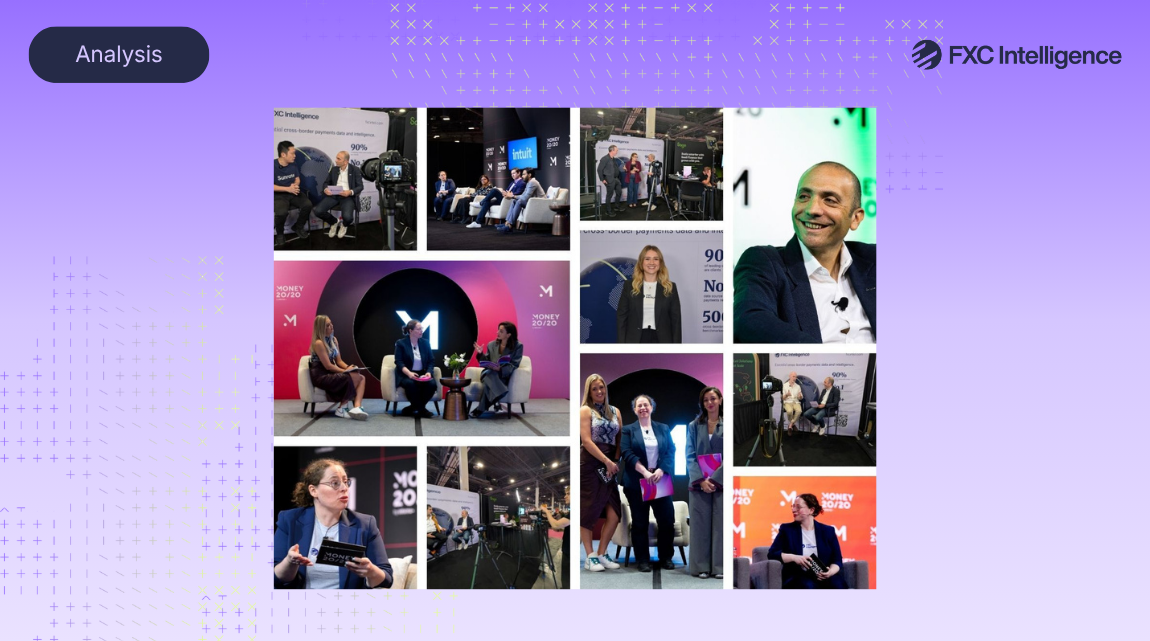
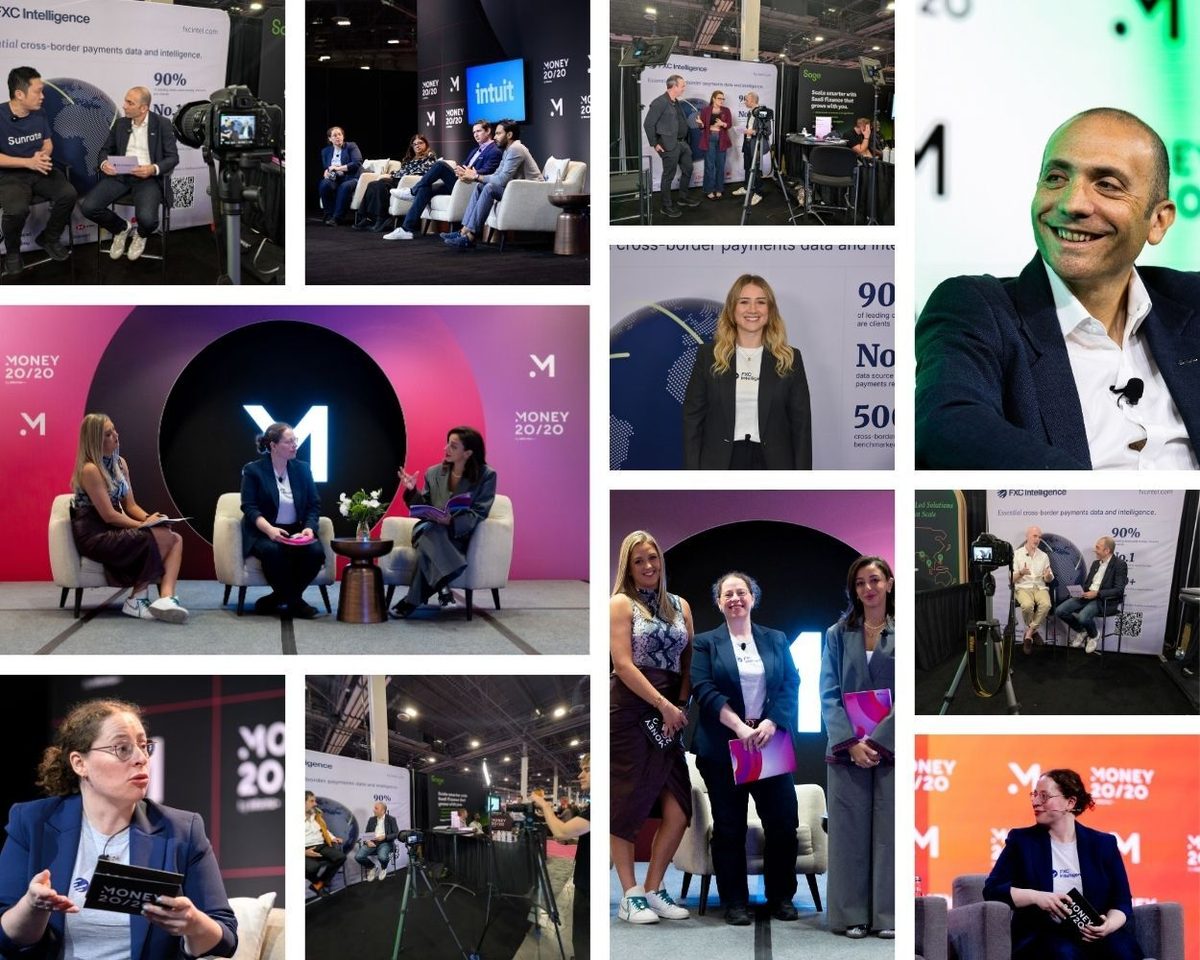
This week, we were on the ground at Money20/20 USA in Las Vegas, US, where we had plenty of insightful conversations about the biggest challenges and trends in cross-border payments amid the usual wave of announcements.
AI has replaced stablecoins as the big focus on the show floor this year. While stablecoins and other digital assets had a strong presence on panels, stands and in some discussions, the industry’s primary attention has shifted more to AI – and in particular agentic AI. Conversations spanned everything from the most effective use of the technology to the potential rise of agentic payments as a key industry area. Those involved in handling such payments are seeing rapid growth. Although headline numbers are still very small, excitement is undoubtedly high.
This year saw a particularly strong presence of cross-border payments on the show floor and in the wider Money20/20 footprint around Vegas. Many major providers showed up in force and it’s clear that there’s significant and growing attention on the global landscape from players in the region.
As has become the norm, meetings were king as the industry prioritises doing business above all else, although there was also very good attendance at the event’s many stages, with a strong array of speakers and a number of last-minute entries and breaking news. As we noted last year, there were also significant numbers of people who showed up to be on the fringes of the event itself, something that may change when the conference moves to the Las Vegas Convention Center in 2027.
Key news and announcements from Money20/20
As usual, several influential companies in the space made cross-border payments announcements of new partnerships and products during the show period this year, which we’ve rounded up below.
- Mastercard has announced a new risk intelligence solution, Stablecoin Security, which uses a combination of payment and blockchain intelligence to help financial institutions assess risk across complex transactions, including cross-border payments.
- Thunes has joined forces with Coinbase, a two-way deal in which Coinbase will power Thunes’ stablecoin infrastructure while Coinbase will integrate Thunes’ Direct Global Network into its platform to power direct payout access to local clearing systems and alternative payment methods.
- Western Union has selected stablecoin infrastructure provider Noah‘s network solution to power its Receiver Redirect service, enabling stablecoin transfers in over 60 currencies across more than 200 countries and territories.
- MoneyGram has relaunched its app and website, and is now using digital asset infrastructure provider Checker to access stablecoin liquidity for its FX operations, boosting its ability to fund payout accounts.
- Visa is collaborating with crypto payments network Mesh in a deal that allows consumers to spend crypto and stablecoin balances at merchants across Visa’s global acceptance network, which spans more than 175 million merchant locations across more than 200 markets.
- Circle and identity infrastructure provider Proof are collaborating to enable AI agents to complete identity-gated purchases, with the agent presenting a verified credential provided by Proof to pay merchants in USDC via a Circle Agent Wallet.
- Klarna has launched Consumer FX, which allows shoppers to buy from connected Klarna agents globally and pay in their own currency with no exchange fees.
- Checkout.com is expanding into in-person payments with a device-agnostic capability enabling merchants to process in-store and online transactions through a single acquiring relationship, with European payments platform Mollie partnering to combine its terminals and point-of-sale software with Checkout.com’s acquiring platform. The service will launch first in the UK and EEA, followed by the US.
- Blockchain infrastructure provider zerohash launched a new infrastructure product, AUTH by zerohash, that structures on-chain asset movement around accounts instead of wallet addresses, removing the need to copy addresses or pick blockchain networks to make transactions and allowing on-chain transfers to work similarly to linking a bank account.